Having a baby is one of life’s most meaningful milestones, but it also brings new financial responsibilities. From hospital bills and newborn essentials to feeding supplies, childcare, and future savings, welcoming a little one can change how a family manages its money.
For many parents, understanding baby expenses in India becomes a priority even before the baby arrives. However, the financial planning doesn’t stop after delivery. As your child grows, everyday costs and family priorities change, making it important to create a budget that can adapt.
The good news is that planning a family budget doesn’t mean buying everything at once or compromising on your baby’s needs. It means understanding your income, identifying essential expenses, preparing for unexpected costs, and making thoughtful decisions as a family.
In this blog, we’ll explore practical ways to plan your family budget after having a baby in India, manage newborn expenses, and build a financial routine that supports your growing family.
1. Understand Your Family's New Financial Situation
The first step in creating a baby budget is understanding how your household finances may change after childbirth.
Your income might remain the same, or it could change if one parent takes parental leave, reduces working hours, or temporarily steps away from work. At the same time, your household spending will likely increase.
Start by reviewing:
- Monthly take-home income of both parents
- Existing rent or home loan payments
- Grocery and household expenses
- Loan repayments and other financial commitments
- Health insurance and medical costs
- Expected baby-related expenses
- Emergency savings and available financial support
Write down your current monthly income and expenses before estimating your new budget.
This gives you a clear picture of how much money is available for your baby’s needs without overlooking existing responsibilities.
2. Calculate Baby Expenses in India Before and After Birth
Baby-related costs generally fall into two categories: one-time expenses and recurring expenses.
Understanding the difference helps you avoid spending too much on newborn shopping while forgetting the costs that continue every month.
One-time expenses
These may include:
- Pregnancy consultations and delivery-related costs
- Baby cot or sleeping arrangements
- Pram or baby carrier
- Car seat, where needed
- Initial clothing and blankets
- Essential feeding equipment
- Basic nursery items
Recurring expenses
These may include:
- Diapers and wipes
- Feeding supplies, if required
- Baby toiletries
- Clothing as your baby grows
- Medical consultations and medicines when needed
- Childcare or daycare
- Additional household expenses
The exact amount varies significantly between families. City, hospital, insurance coverage, feeding choices, childcare arrangements, and whether you purchase new or second-hand items can all affect your spending.
Rather than relying on a single estimated cost, prepare your own list based on your circumstances.
3. Create a Monthly Budget for Your Growing Family
Once you have an idea of your baby’s expenses, create a monthly budget that includes both household and baby-related spending.
A simple budget should cover:
|
Expense category
|
What to include
|
|---|---|
|
Housing
|
Rent, home loan, electricity, water
|
|
Household
|
Groceries, cooking gas, transport
|
|
Baby essentials
|
Diapers, clothing, toiletries
|
|
Healthcare
|
Doctor visits, medicines, vaccinations
|
|
Childcare
|
Daycare, nanny, or other arrangements
|
|
Savings
|
Emergency fund and future goals
|
|
Personal spending
|
Occasional outings and other family needs
|
A 2026 report by The Economic Times discussed an estimate of around ₹18,000 in monthly child-related upbringing expenses, but actual costs depend on the family’s location, lifestyle, and what expenses are included. Treat such figures as reference points, not fixed budgets.
4. Prepare for Medical and Healthcare Expenses
Healthcare is an important part of planning baby expenses in India.
Depending on your circumstances, you may need to budget for paediatric consultations, vaccinations, medicines, and unexpected medical visits. Pregnancy and delivery expenses may also affect your finances during the early months of parenthood.
Before assuming that insurance will cover everything, review your policy carefully. Check maternity benefits, newborn coverage, waiting periods, exclusions, and any limits that apply.
You can also ask your hospital or healthcare provider for an estimate of expected charges and clarify which expenses may be separate.
Keep a dedicated medical buffer within your emergency savings. This can help your family manage unexpected bills without having to depend entirely on credit cards or loans.
5. Buy Baby Essentials Without Overspending
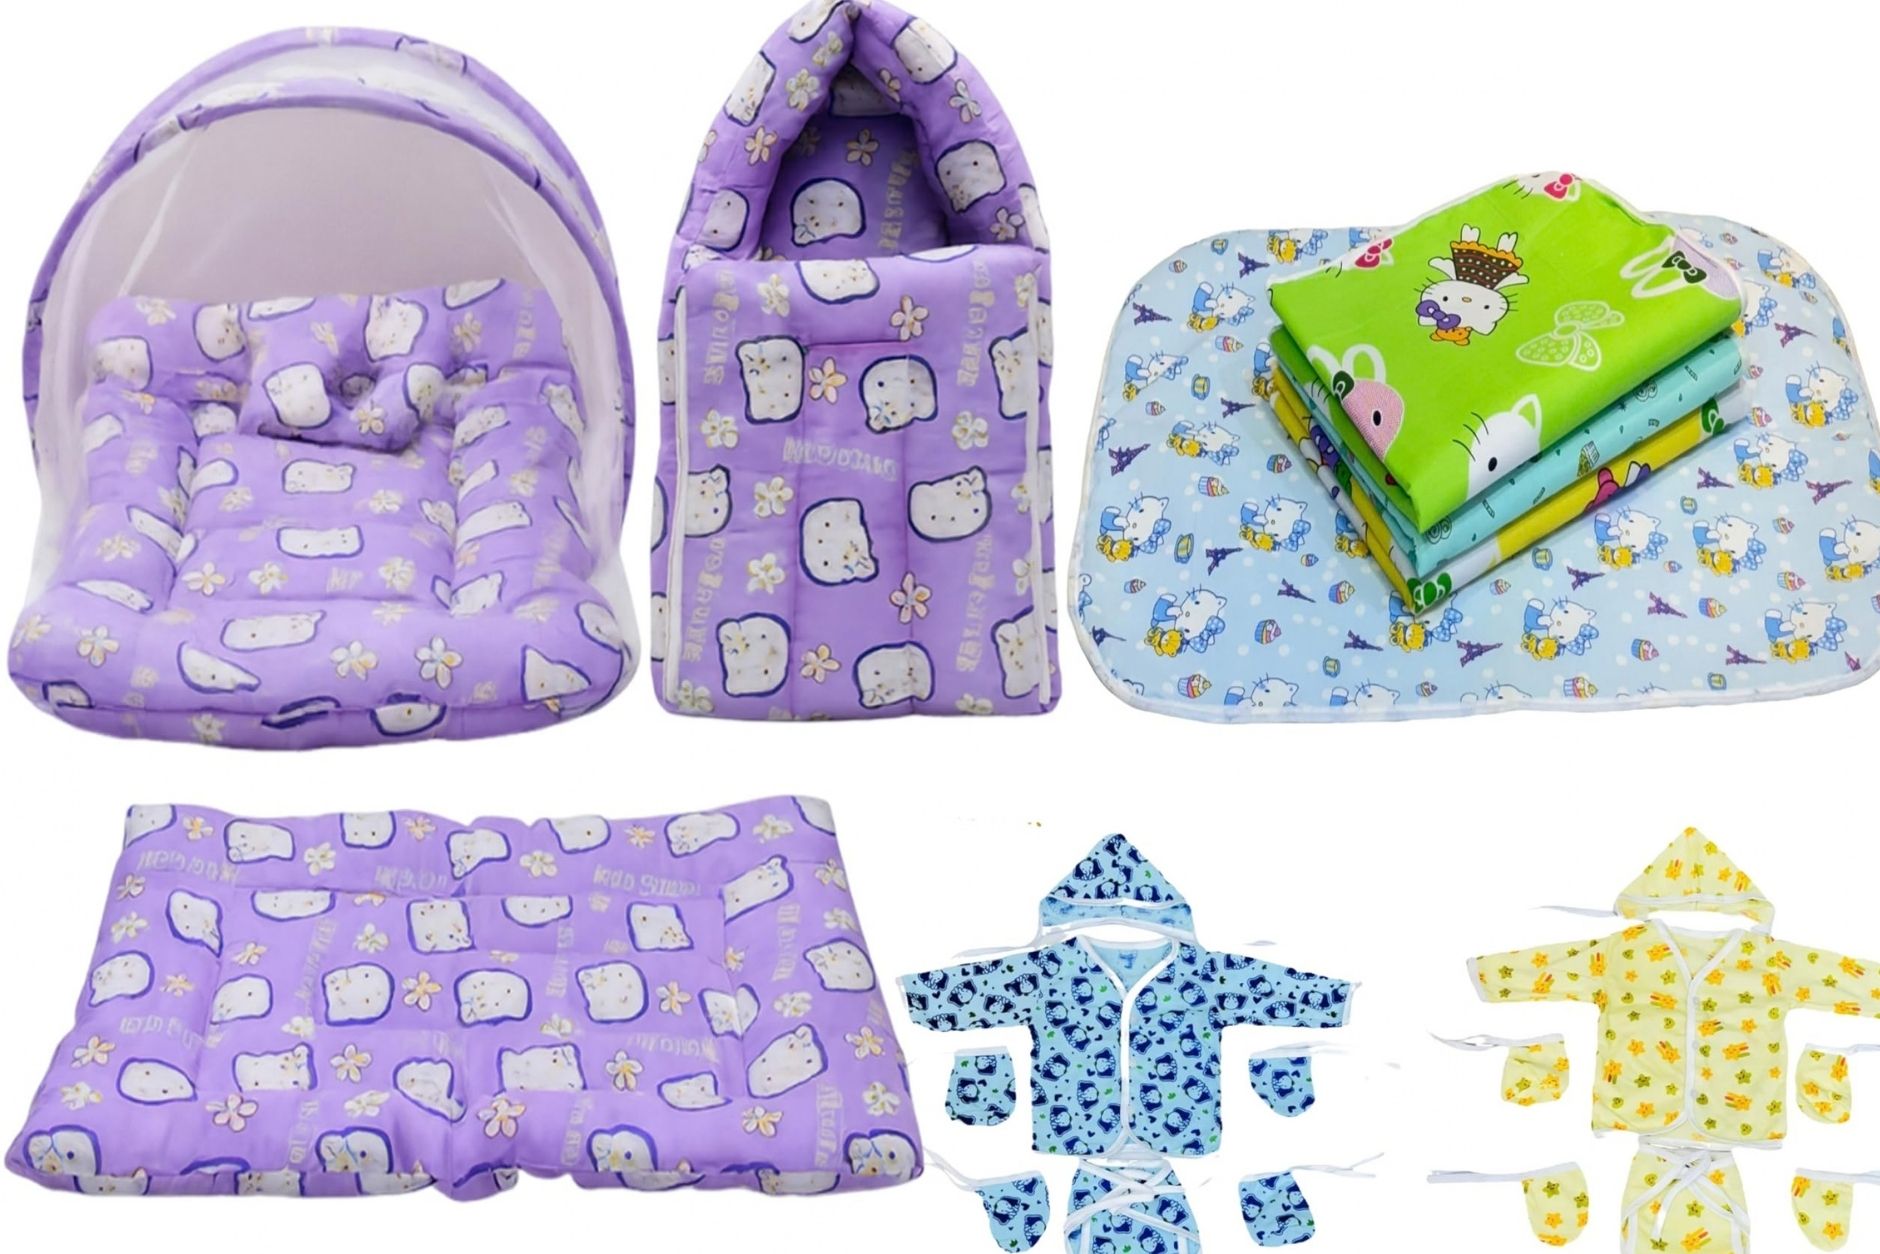
New parents often feel pressure to prepare everything before the baby arrives. Online shopping lists, social media, and recommendations from friends can make it seem like a long list of products is essential.
However, many purchases can wait until you understand your baby’s needs.
Start with the basics:
- Comfortable, washable baby clothes
- Safe sleeping arrangements
- Diapers or cloth nappies
- Feeding essentials appropriate to your situation
- Bathing and hygiene supplies
- A thermometer and other appropriate basic care items
Consider borrowing or buying suitable second-hand items when practical. Clothes, for example, may only be used for a short period before your baby outgrows them.
For safety-critical items such as car seats and sleep equipment, check current safety guidance and the item’s condition before buying second-hand.
A useful rule is to purchase essentials first and delay non-essential gadgets, elaborate nursery decorations, and large quantities of newborn-sized clothing.
6. Plan for Childcare and Changes in Income
Childcare can become one of the biggest ongoing expenses for families, particularly when both parents return to work.
Before making a decision, compare the available options:
- Daycare or crèche
- A nanny or other paid childcare arrangement
- Support from family members, where available
- Adjusted working hours or a temporary career break
Each option has financial and practical considerations.
For example, paid childcare creates a direct expense, while a career break may reduce household income and affect future career progression. Family support may reduce some costs, but availability and expectations differ from household to household.
Calculate the actual difference between your income before and after childcare costs. Also consider commuting, meals, work-related expenses, and the value of maintaining both careers.
Discuss these decisions with your partner early so that childcare arrangements do not become a rushed financial decision after parental leave ends.
7. Build an Emergency Fund for Your Family
An emergency fund becomes especially important when you have a dependent child.
Unexpected expenses may include medical bills, a temporary loss of income, urgent travel, or a sudden change in childcare arrangements.
A practical starting point is to aim for around six months of essential household expenses. Families with irregular income or a single primary earner may prefer a larger buffer, depending on their circumstances. HDFC Bank’s 2026 new-parent checklist also highlights emergency savings as an important part of family financial planning.
8. Start Saving for Your Baby's Future
Although your baby’s immediate needs deserve attention, it is also worth thinking about longer-term goals.
These might include education, extracurricular activities, future healthcare, or other opportunities as your child grows.
You don’t need to make large investments immediately. Begin by identifying your goals, the approximate time available, and how much your household can comfortably save.
You could set up a separate savings account or explore suitable investment options based on your financial situation, risk tolerance, and time horizon. Investments such as mutual funds carry market risk, so understand the product before committing money.
Remember that saving for your child’s future should not come at the expense of essential household expenses, emergency savings, or your own retirement planning.
A balanced family financial plan considers everyone’s needs.
9. Track Expenses and Review Your Budget Every Month
Your first family budget will probably need adjustments. A newborn’s needs change quickly, and expenses may vary from one month to another.
Choose a tracking method that works for you. It could be a spreadsheet, a budgeting app or a simple notebook.
At the end of each month, review:
- What you actually spent on your baby
- Which costs were higher than expected
- Whether any planned purchases can wait
- How much you saved
- Whether your income or childcare arrangements have changed
Try to review the budget together with your partner. This can help both parents understand where the money is going and make decisions without placing the entire financial responsibility on one person.
Even a short monthly conversation can help your family stay organised.
10. Make Room for Family Life, Not Just Expenses
Budgeting after having a baby is not about cutting every enjoyable activity from your life.
Parents also need opportunities to rest, spend time together, and enjoy meaningful family moments.
Instead of feeling guilty about every non-essential purchase, include a realistic amount for personal spending and family activities. This might cover an occasional meal out, a small family outing, or a practical purchase that makes daily life easier.
The key is to make these decisions intentionally, rather than allowing unplanned spending to interfere with essential bills or savings.
A family budget should support your life with your baby, not become another source of stress.
Conclusion
Planning baby expenses in India is an important step towards creating a financially comfortable home for your growing family. From healthcare and newborn essentials to childcare, emergency savings, and future education, every stage of parenthood brings different financial priorities.
The key is to start with a realistic family budget, focus on your baby’s essential needs, and make adjustments as your circumstances change. You don’t need to purchase everything at once or have every financial decision figured out immediately.
Build your emergency fund gradually, review your insurance, track monthly spending, and discuss important financial decisions with your partner. Even small, consistent savings can help you prepare for future responsibilities.
Most importantly, remember that every family’s financial situation is different. Your budget should reflect your income, location, childcare arrangements, and personal priorities rather than someone else’s spending habits.
At Mommies.in , we understand that parenthood comes with plenty of questions, changes, and new experiences. Our parenting resources are here to support you as you navigate pregnancy, motherhood, baby care, and family life.